

Industry: Transportation
Product: ModelRisk
Application: Logistics Planning
Picking a Fifth DC: Memphis, Dallas, or Salt Lake City Under Five Years of Stochastic Demand
A national retailer with a four-distribution-center network across the U.S. needed a fifth DC. The deterministic site-selection model ranked the three finalists — Memphis, Dallas, Salt Lake City — by computing each candidate's expected 5-year cost reduction against the current 4-DC baseline (mean baseline cost: $188 million a year). The deterministic ranking said Memphis wins. The Monte Carlo rebuild in ModelRisk said something more useful: Memphis and Salt Lake City are statistically tied on expected NPV savings (about $21M and $20M respectively), each is the best of the three on roughly half the scenarios (Memphis 51%, Salt Lake City 47%), and Dallas is almost never best (2%) despite reading as a respectable middle option deterministically. The real choice is between two near-identical NPVs at very different capex — exactly the trade a single point estimate hides.
A network-design study rebuilt the candidate-comparison in ModelRisk with coupled demand and LTL-rate uncertainty. The savings-distribution view is what reframed the decision.
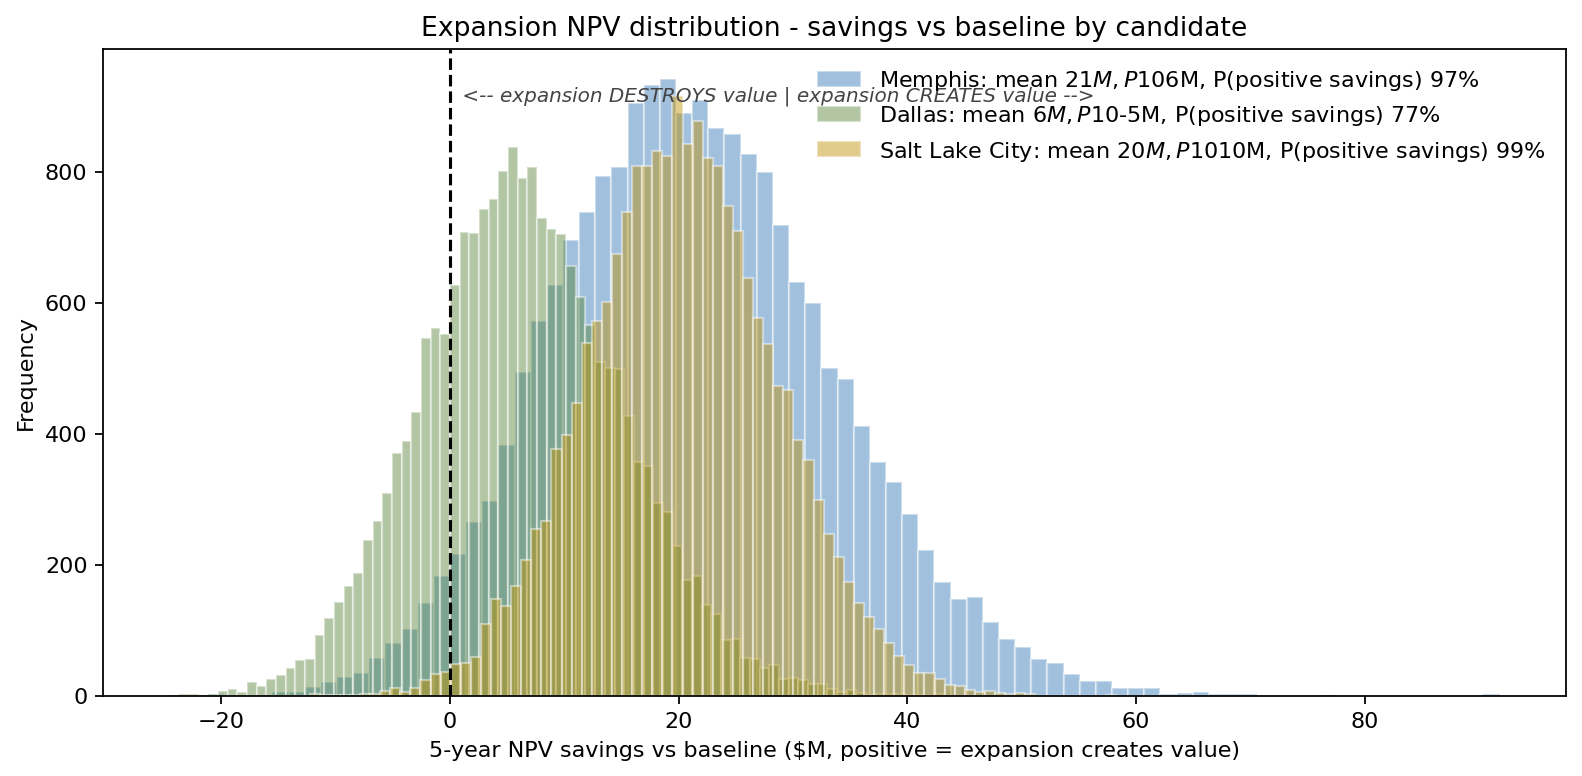
Each curve is the distribution of (baseline NPV − candidate NPV) — money saved on the right, value destroyed on the left. Memphis and Salt Lake City sit almost on top of each other near a $20-21M mean saving, both with a tiny probability of destroying value (Memphis ~3%, Salt Lake City ~1%). Dallas trails badly: a $6M mean saving and a 23% chance of destroying value outright, dragged down by its $92M capex. The deterministic ranking's "Memphis wins" is true only at the decimal point — the distribution shows the genuine contest is Memphis vs Salt Lake City, and it is a coin-flip on cost.
What the model gets right that a forecast doesn't
The 5-year network cost is dominated by two stochastic inputs:
Annual demand growth was fitted as AR(1) around a 3.4% long-run rate, with annual innovation standard deviation 2.8% — the residual from the company's historical demand series after removing trend and seasonality. Over 5 years this produces a Year-5 demand multiplier with mean 1.13, P10 0.97, P90 1.30. The deterministic plan uses the central 1.13 flat; the stochastic plan sees the spread — including the real chance (P10 below 1.0) that demand actually contracts.
LTL freight rate index was fitted as AR(1) with annual vol 12% around the long-run base — capturing the cyclical cap-tightening of the U.S. LTL market, with a Year-5 index spanning P10 0.82 to P90 1.19. Critically, demand and LTL rate are coupled via a Gaussian copula on the underlying shocks (shock correlation 0.45): high-demand years tend to be high-LTL-rate years, because tight national capacity drives both. The AR(1) smoothing dilutes that to a realized Year-5 demand/rate correlation of about 0.27. Modeling the two inputs as independent — the previous deterministic-style site model — undercounts the right tail of the cost distribution.
The candidate-specific savings are what differentiate the three sites:
- Memphis — hub-and-spoke central location, large transport savings (~$22M/yr mean, sd $5.5M), moderate inventory savings ($7M/yr), $78M capex. But Memphis transport savings are highly sensitive to LTL rate (β = 1.20 in the rate-index): when LTL rates spike, the hub-and-spoke savings shrink because Memphis is the lane-flow concentrator.
- Dallas — balanced transport savings (~$19M/yr, sd $3.8M, lower variance), higher inventory savings ($9M/yr), highest capex ($92M). LTL sensitivity lower (β = 0.85).
- Salt Lake City — smaller transport savings ($14M/yr) but the best inventory savings ($11M/yr) because the site decouples east-of-Rockies and west-of-Rockies fulfillment, cutting safety-stock duplication. Lowest capex ($65M). LTL sensitivity smallest (β = 0.55) because most SLC flows are intermodal-rail-fed.
What the deterministic ranking missed

The CDFs of total 5-year NPV cost tell the same story as the savings view. The 4-DC baseline (mean $766M, P90 $846M) is the most expensive everywhere. Memphis (mean $744M, P90 $817M) and Salt Lake City (mean $745M, P90 $823M) are nearly coincident across the whole range — Memphis holds a hair-thin lead at the central case and at the right tail, where its larger transport savings outweigh Salt Lake City's lower LTL-rate sensitivity. Dallas (mean $759M, P90 $835M) sits clearly worse than both.
For a retailer whose creditor covenants weight tail cost heavily, the useful finding is not a clean tail-winner — it is that Memphis and Salt Lake City deliver indistinguishable cost distributions, so the decision must be made on the dimensions the cost NPV cannot separate: capex outlay, build risk, and network resilience. That reframing cannot come from a deterministic ranking that simply reports "Memphis wins."
What separates the two front-runners
This is the "Why Monte Carlo" beat in network design. The savings distribution at the top of this article shows Memphis and Salt Lake City as near-twins on cost — mean savings $21M and $20M, value-destruction probabilities 3% and 1%. Memphis carries the marginally higher mean and the marginally fatter left tail; Salt Lake City is fractionally more reliable but saves a touch less. Dallas is the clear laggard: a $6M mean saving and a 23% chance of destroying value, the penalty for its $92M capex.
Because the two front-runners are statistically tied on cost, the differentiators are the inputs that don't show up in the NPV mean: Salt Lake City's $65M capex is $13M lighter than Memphis's $78M, and its east-/west-of-Rockies decoupling adds west-coast port-flow resilience that the cost model does not price. Memphis's higher LTL-rate sensitivity (β = 1.20 vs 0.55) means its slim cost lead is also the first to erode if national freight markets tighten harder than the copula assumes.
What actually drives the Memphis NPV savings

The baseline the tornado decomposes is Memphis's $21M mean NPV saving. Demand growth rate is the biggest mover, followed by Memphis's own transport-savings calibration uncertainty, then LTL-rate-index volatility. Critically, the demand-LTL correlation is a meaningful mover in its own right, and it is exactly the parameter the previous deterministic model implicitly set to zero. The Memphis-vs-Dallas mean-NPV gap is only about $15M — small enough that a parameter the deterministic model ignored entirely can reorder the ranking.
From insight to action
- Salt Lake City selected as the fifth DC. With its cost NPV statistically tied to Memphis (mean savings $20M vs $21M; value-destruction risk 1% vs 3%), the decision was made on the dimensions the cost model could not separate: a $13M lighter capex ($65M vs $78M), a near-zero chance of value destruction, and west-coast resilience. The lighter capex preserves more headroom under the retailer's lender fixed-charge-coverage covenant.
- Memphis kept as a Phase-2 trigger. A trigger-clause was added to the network plan: if year-2 actual LTL rates settle below an index of 0.95, the Memphis option re-opens as a Phase-2 expansion — capturing the upside in exactly the low-rate scenarios where Memphis's higher transport savings and LTL sensitivity work in its favour. The Monte Carlo distribution priced this real option at $11M of additional expected NPV value, justifying the $1.4M cost of holding the Memphis site under purchase option.
- Inventory and safety-stock policy updated to reflect the bicoastal-decoupling savings that SLC unlocks but Memphis does not. The reorder-point recalculation alone is worth roughly $4.8M/year in carrying cost the deterministic plan had attributed entirely to "transport savings."
ModelRisk Functionality Used
- Gaussian-copula coupling of demand and LTL-rate paths (shock correlation 0.45, realized Year-5 correlation ~0.27 after AR(1) smoothing), capturing the cyclical co-movement that pure deterministic site-selection ignored.
- AR(1) demand growth modeling with shock SD calibrated to the historical residual, replacing the prior "flat 3.4% growth assumption" that had hidden the Year-5 demand spread of P10 0.97 to P90 1.30.
- Location-specific savings distributions (Normal on the savings line with per-site mean and SD calibrated to engineering studies) — including per-site LTL-rate sensitivity coefficients (β = 1.20, 0.85, 0.55) that the prior site-selection spreadsheet had set to a constant 1.0.
- 20,000-scenario NPV simulation producing the full distribution of 5-year network NPV cost for each candidate plus the baseline, with paired draws so candidate-vs-candidate ranking is apples-to-apples.
- Real-option valuation of the Memphis Phase-2 trigger — computed as the expected value of (NPV under low-LTL scenarios) × P(trigger activates) — pricing the option at $11M and justifying the $1.4M holding cost in the capital plan.
- Tornado decomposition of Memphis's $21M NPV saving, surfacing the demand-LTL correlation — the parameter the deterministic model had implicitly set to zero — as a driver large enough to matter against a $15M Memphis-Dallas gap.
A distribution-center decision is a multi-year bet on a joint distribution of demand growth and freight-market cycles. Monte Carlo simulation in ModelRisk gives the network-design team the joint distribution and the per-candidate savings shape — and shows that the two front-runners are tied on cost, letting the CFO defend the choice on capex, reliability, and resilience rather than a spurious mean-NPV gap, which is exactly the language the lenders speak.