

Industry: Banking and Financial Services
Product: ModelRisk
Application: Long-horizon investment strategy under uncertainty
The deterministic plan says $65k/year in retirement. The simulation says a 1-in-4 chance of less than $40k.
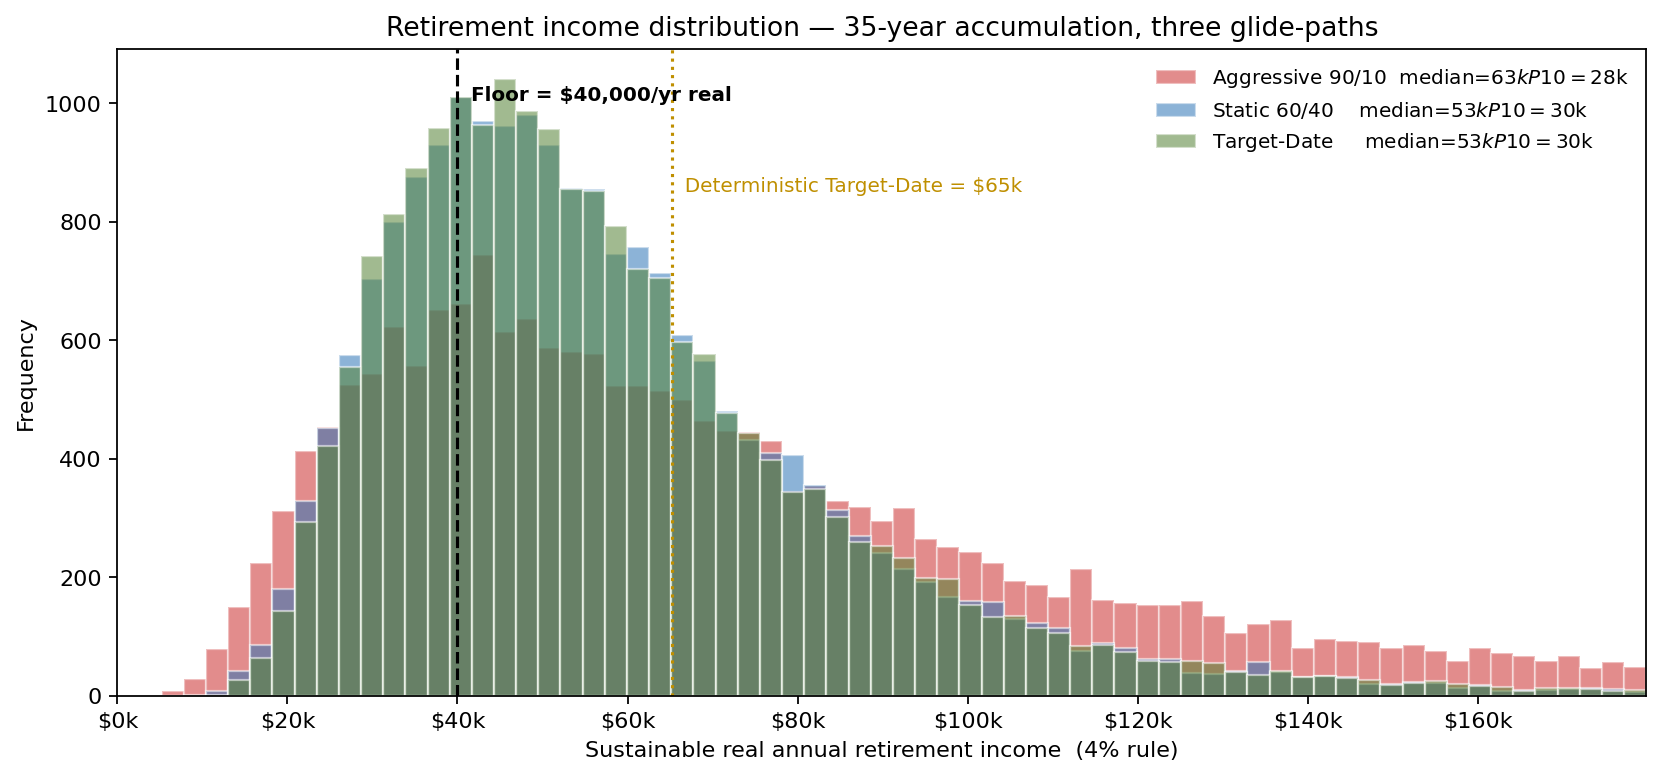
A 30-year-old wealth-management client with a $72,000 starting balance and a $14,500 annual contribution sat in front of a target-date fund pitch deck that promised, on its compounded-mean spreadsheet, a sustainable real income of roughly $65,000 per year in retirement. The Monte Carlo re-projection of the same glide-path, with stochastic returns and the historical crash-frequency mix, showed the median was only $53,000, the P10 outcome was $30,000, and the probability of falling below the client's $40,000 income floor was 26% — better than one retirement in four. That gap — between the planner's compounded-mean number and the actual distribution — is what every individual retirement plan that ignores volatility silently gives away.
Stochastic returns instead of compounded means
Compounding 6.5% real equity returns and 1.8% real bond returns over 35 years gives a single number. Compounding them with their actual variance — equity \(\sigma = 16\%\)/yr, bond \(\sigma = 6\%\)/yr, correlation \(\rho \approx 0.15\), plus a 3%/year mixture for an equity crash event of -25% — gives a distribution. The two answers diverge because real wealth accumulation is path-dependent: the same arithmetic mean can land at very different terminal balances depending on when the bad years arrive. The compounded-mean projection ($65k) is not the median of the compounded paths ($53k); the difference is the volatility drag a point estimate cannot see.
The model uses Normal innovations for both asset classes (defensible at annual frequency for diversified indices) plus a Bernoulli crash mixture that lifts the equity tail without polluting the body of the distribution. Returns are correlated via the standard linear-mixture construction. The contribution schedule is real (inflation-adjusted) at $14,500/year for 35 years; the starting balance is $72,000.
Three glide-paths, three very different downsides
The client was comparing three strategies (shown in the opening chart): a Static 60/40, a Target-Date glide-path from 90/10 at age 30 to 40/60 at age 65, and an Aggressive 90/10 held throughout. The shape of the income distribution is what differs.
The Aggressive 90/10 strategy has the highest median (~$63k/yr real) and by far the fattest upper tail (P90 ~$145k), but also the lowest P10 (~$28k) because there is no de-risking buffer when a late-career drawdown hits the largest-ever balance; even so its higher median holds its floor-breach probability to about 24%. The Target-Date and Static 60/40 glide-paths both centre on a median near $53k with a P10 around $30k and a floor-breach probability of about 26–27% — a lower ceiling than Aggressive, but a slightly higher floor.
The deterministic Target-Date projection — drawn as the dotted amber line at $65k — sits well above the $53k median of the actual distribution. This is the compounding-of-the-mean fallacy: the mean of the compounded path is not the path of the compounded mean.
Why Monte Carlo, not a point estimate?
The CDF view makes the trade-off impossible to miss.
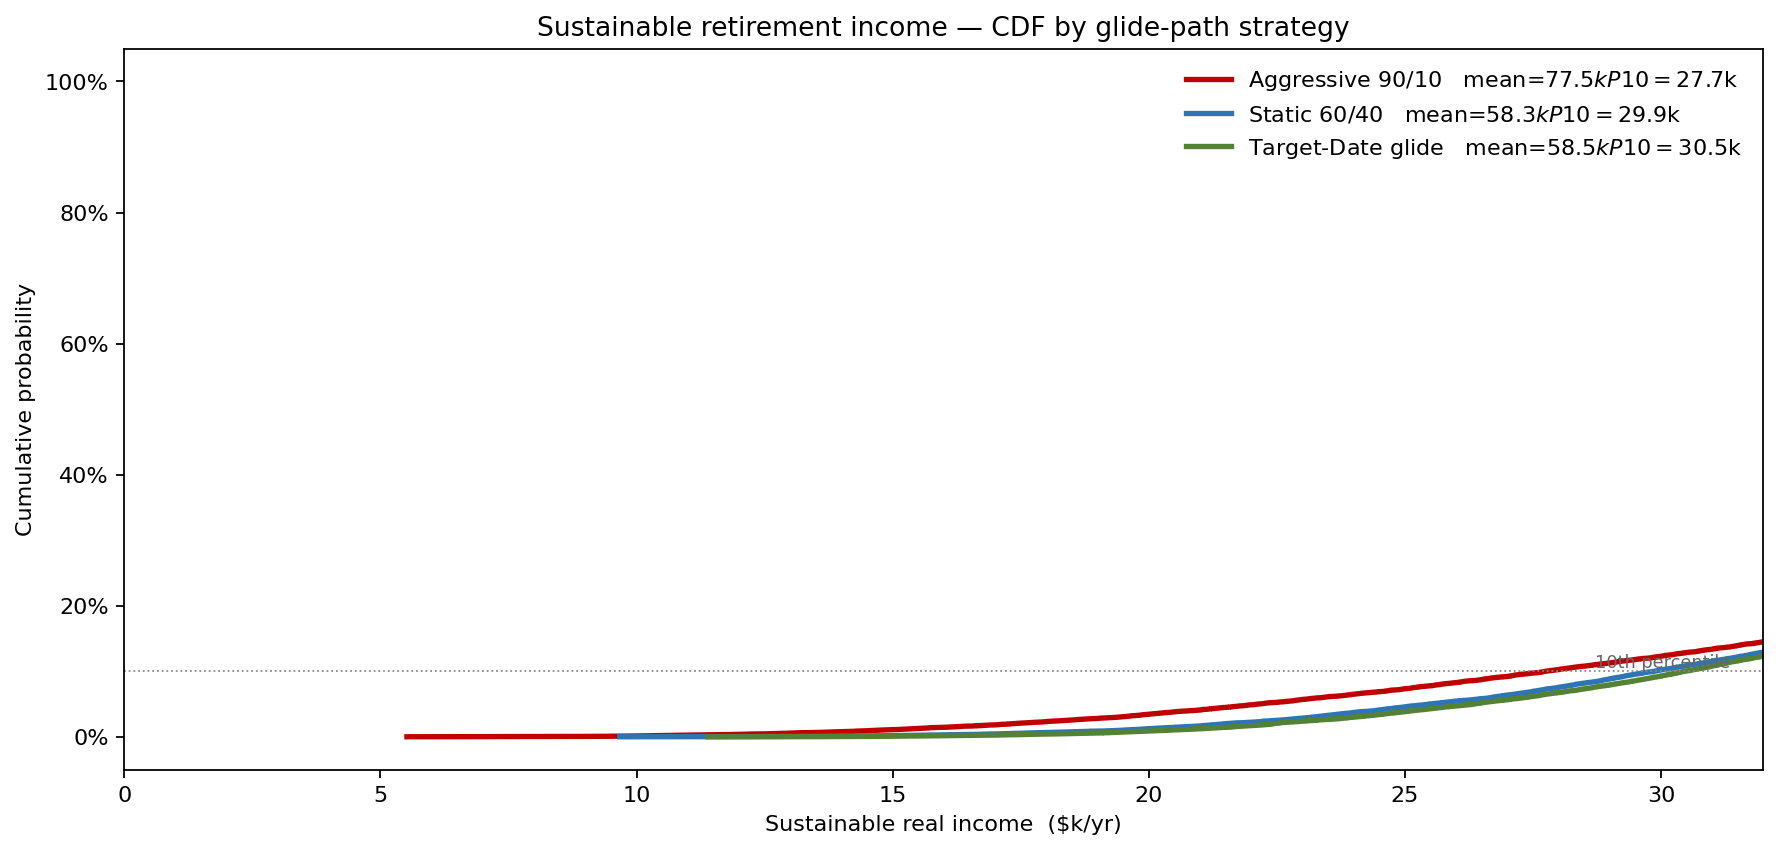
At the 10th percentile, the Target-Date strategy delivers roughly $30.5k/yr, the Static 60/40 about $29.9k/yr, and the Aggressive 90/10 only $27.7k/yr. At the 90th percentile the order reverses — Aggressive (~$145k/yr) wins by about $51k/yr over the Static 60/40 (~$93k/yr). The point estimate ranks these three identically because it sees only the means. The simulation makes the actual question available: given the client's $40k floor, what is the cheapest amount of upside they need to give up to push the failure probability below 10%?
What actually moves the P10 income
A tornado on the P10 income of the Target-Date strategy ranks the levers the planner can pull.

Equity volatility, not equity return, is the largest driver of the P10 — a 7-point swing in assumed annual sigma (15% to 22%) moves P10 income by roughly $4,200/year. The expected equity return matters second. The contribution rate matters next — raising the contribution from $14.5k toward $17k/year buys roughly $3,100/year of P10 income, more than the glide-path slope buys. The correlation between equities and bonds, often debated, is near the bottom of the list — useful news for clients who agonize over rebalancing rules but not over the actual return assumptions.
Sequence-of-returns risk made visible
The single feature deterministic projections cannot represent at all is when the returns arrive. The simulation made it visible.
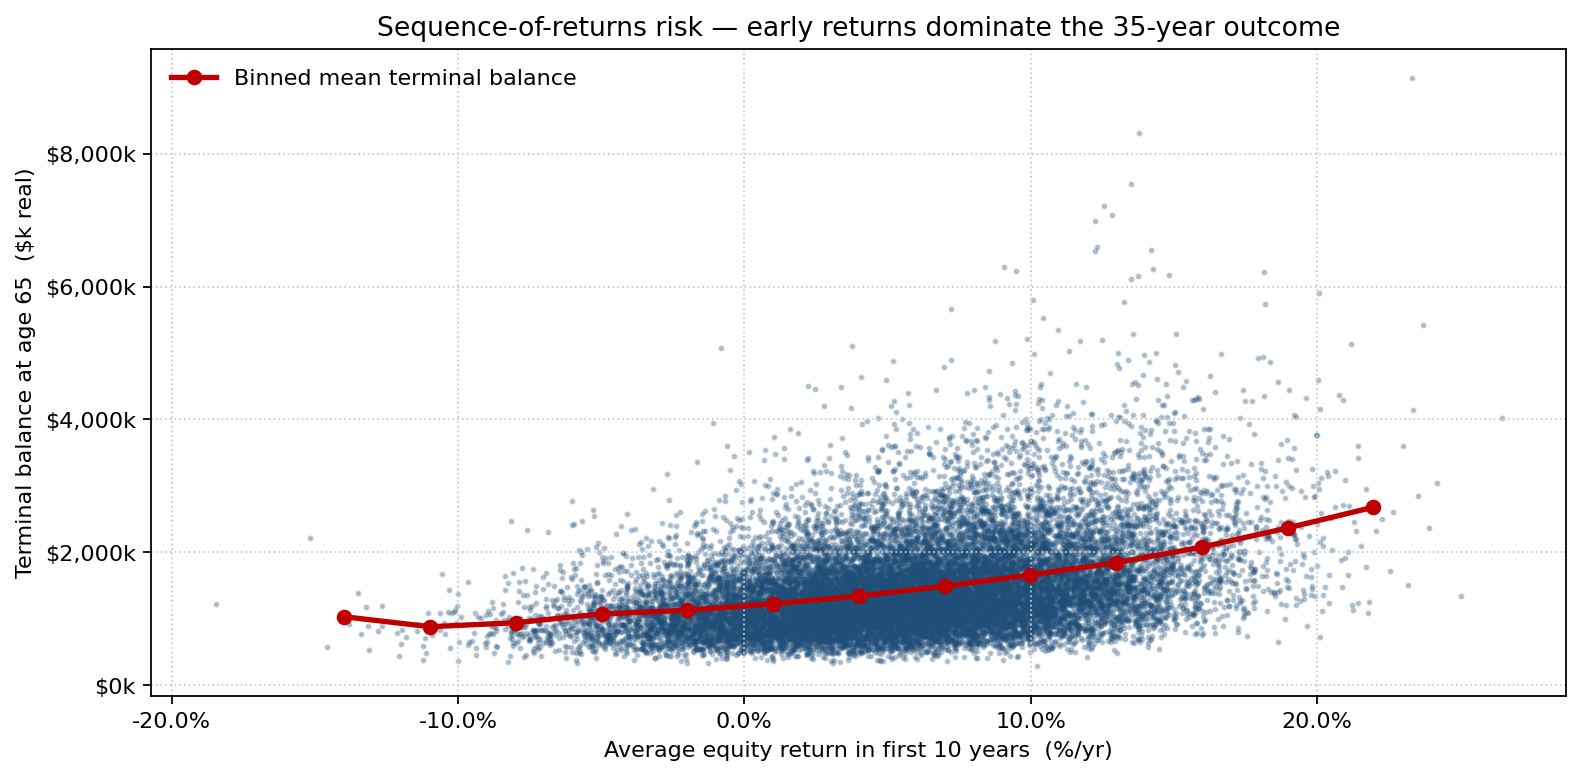
Each grey dot is one simulated lifetime. The red curve is the binned-mean terminal balance as a function of the average equity return in the first ten years. The realised terminal balances span from about $0.66M (P5) through $1.31M (median) to $2.78M (P95) — and almost all of that spread is explained by the first decade, a much steeper gradient than the same swing in the last decade would produce. This is the mathematical reason a glide-path that de-risks late, rather than early, makes sense: the largest portion of the path-dependent variance lives in the early years' interaction with the smaller balance.
From insight to action
The headline finding reframed the whole conversation: the deck's comfortable $65k figure carries a 26% probability of landing below the client's $40k floor, with a bottom-decile income near $30k. The client adopted the Target-Date strategy with three adjustments derived directly from the simulation:
- A contribution buffer. The tornado shows a $14.5k-to-$17k increase buys roughly $3,100/yr of P10 income — the most direct lever for pulling the floor-breach probability down toward the client's risk tolerance.
- First-decade volatility cap. During the first 10 years, the equity bucket is held at 75% rather than the glide-path's 90%, accepting a modestly lower median income in exchange for a thinner left tail. The trade was visible only because the sequence-of-returns chart isolated which decade owned the risk.
- Annual replan, not the prospectus glide-path. The client's actual glide-path is now re-optimized each year against the current balance and remaining horizon, rather than tracking the prospectus curve.
ModelRisk functionality used
- 20,000-path 35-year wealth accumulation with correlated real returns (equity Normal + crash mixture, bond Normal, \(\rho = 0.15\)).
- Glide-path comparison via overlaid income distributions — Static 60/40, Target-Date, Aggressive 90/10 — quantifying medians and P10s rather than presenting a single compounded-mean number.
- Tornado sensitivity on P10 income — ranked seven planning levers, identifying equity volatility as the largest contributor, ahead of equity return itself.
- Sequence-of-returns scatter — terminal balance vs first-decade equity return, exposing the asymmetry that justifies an early-life vol cap.
- Conditional metric: P(income < $40k floor) — used as the binding acceptance criterion for the client plan, replacing the prior "expected income exceeds floor" check.
The lesson is the one every long-horizon investor has to internalize once: a 35-year plan is not a forecast, it is a distribution of forecasts, and the difference between the median and the P10 is the part of the plan that actually requires a decision.